There’s always mistales

Greyscale backing image
[Dave Birch] Well, this is interesting. One of my mobile phone operators (I currently have three: my iPhone, my dongle and my son’s phone) has sent me someone else’s bill. I now have someone’s name, address (why it came through our door I have no idea: the address isn’t even in the same town, let alone the same street), mobile number and an itemised bill. I’m sure I could get up to some mischief with this. I don’t want to pick on mobile operators in particular, but I do want to point out that this sort of thing will always happen. In a bizarre way, we’ve come to expect them. It’s even vaguely comforting to read about the usual colossal cock-ups with computers, because it reassures you that all is right with the world…

Zamora said the pump at the By-Pass Deli and Conoco service station at Stevens Drive and the Highway 240 Richland bypass registered only $26 for the fuel. But somehow the transaction was recorded on his debit card as totaling $81,400,836,908… After learning that afternoon by e-mail that his debit card was maxed out (no kidding! ed.) he called customer service… “Somebody from a foreign country who spoke in broken English argued with me for 10 to 15 minutes,” Zamora said. ” ‘Did you get the gas?’ he asked. Like I had to prove that I didn’t pump $81,400,836,908 in gas!”

[From Local News | How many billion dollars for that tank of gas? | Seattle Times Newspaper]

I am literally astonished that a charge for $81 billion could go through the debit card system at all. Wouldn’t you have thought that the settlement system had some limit minding in it that will trigger if a transaction for more than, oh I don’t know, let’s say A BILLION DOLLARS comes through on a debit PAN? Clearly, whoever built the system never imagined that this could happen, so they never put in any logic to watch out for it.

It’s crazy to build systems on the assumption that nothing will go wrong. Amusingly, in a tragic and depressing kind of way, this was reinforced by the news that public employees have already been snooping around in the proto-national identity register to look up friends, family and presumably other “interesting” people even though it’s not even been built yet. Still, not to worry. So far it’s only 30 local authorities that have noticed a problem.

Staff at 30 local authorities have been responsible for “serious security breaches” in the government database that will form the core of the national ID cards programme. Local authority staff have viewed sensitive personal records on the Customer Information System (CIS) run by the Department for Work and Pensions (DWP), it emerged today. The £72m Customer Information System is an Oracle database being built by Accenture for the Department for Work and Pensions. It will hold a wide variety of data on nearly all UK citizens.

[From ID Cards insider: scheme is “largest , most complex and sensitive undertaking in Government” (Tony Collins’s IT Projects Blog)]

Why on earth would anyone have imagined that there would be any other outcome? And by the way, if I was one of these public employees snooping around for the purposes of amusement, I’d have been using someone else’s username and password, so there’s no real chance of catching them.

Announcing Identity & Privacy 2009

Greyscale backing image
[Dave Birch] Here’s another date for your calendars: London, 14th an 15th May 2009. The Digital Identity Forum and the Enterprise Privacy Group will be hosting the first Identity & Privacy Forum, sponsored by Consult Hyperion with support from HP, Microsoft, Symantec, Verisign and VoicePay. The Forum will be held at the Guoman Charing Cross Hotel, London, and I’m looking forward to seeing you there. Toby Stevens and I will be sending out a detailed agenda in a couple of weeks, but just as a heads-up there are going to be four sessions: “a snapshot of electronic identity”, “co-evolving privacy and consent”, “sharing front line experiences” from the public sector and “catching up with biometrics”.

We’ll be sending out the agenda in a couple of weeks and fleshing out the expert panels. As soon as we do, you’ll be able to buy tickets!

At whose fingerprints?

Greyscale backing image
[Dave Birch] I went to the Social Market Foundation chat about biometrics sponsored by the Identity and Passport Service (IPS). The speakers — Jim Wayman from San Jose State University, Peter Hawks and Hugh Carr Archer (Aurora) from our friends at IAFB, Farzin Deravi from the University of Kent and forum friend Toby Stevens from EPG — got a good discussion going although personally I thought it was a little too short. I was very interested in some of the points being raised from the floor and would have appreciated more time for expert reflection from the panel.

Jim started his talk by referring to the “colourful” history of the future of biometrics, which appealed to my current obsession with paleo-futures at the CSFI, and made a couple of points that I think are worth opening up for discussion here. First of all, he made the key point that biometrics doesn’t solve the problem of identification but once you have identified someone then you can use biometrics to link them to that identity. Biometrics is easy, identification isn’t, and biometrics do not guarantee the validity of non-biometric data in database (this is why I keep promoting the “biometric only” plan from the UK National Identity Register). Secondly, he made me reflect on the difference between schemes where the “users” care about multiple uses or not. So, if I have a season ticket for the London underground, I don’t care about my brother using it on the days that I’m not. But I don’t want him using my credit cards on days that I do not. So why would you need a biometric for a bank card? Good point. I think that the answer is that if we want to use cards for larger transactions then we can’t use PINs because PINs are too easily snaffled, but I’m going to think some more about this and post in the future.

Payments without banks

Greyscale backing image
[Dave Birch] We implicitly associate the notion of payments with the notion of banks but, as I often point out, this reflects current arrangements not laws of physics. Michael Linton’s mention of the “Irish bank strike” example of a modern economy functioning without bank services at the retail level reminded me of this. He points out:

For several months, almost a year from start to finish, the Irish did it all with their own paper and no banks.

[From kashklash:: exchanging the future » Blog Archive » The Irish answer]

What’s the story? Well, between 1966 and 1976 there were three major “all out” bank strikes in Ireland that shut the retail banks for (in total) a year. There is a super case study, written a few years ago, on this called “Money in an Economy Without Banks” by Antoin Murphy of Trinity. I’ve sometimes referred to it when challenging people to think harder about how the payment system works, but of course it’s taken on a new lease of life in current circumstances and in the context of the “utility vs. casino” strategy discussions.

Back to Ireland. The case study notes that about four-fifths of the money supply disappeared because of the bank strikes, so the general public were left with the notes and coins in their pockets and nothing else. How did this society function? Since people could not go to the bank and draw out more money, they developed their own currency substitutes: some people began to use Sterling instead, but it was the cheque that stepped in to keep the economy going. People began to accept cheques from each other, and these cheques began to circulate.

In summary a highly personalised credit system without any definite time horizon for the eventual clearance of debits and credits substituted for the existing institutionalised banking system.

Murphy points out that one of the key reasons why a “personalised credit system” could substitute for cash was the local nature of the circulation — which, as Michael Linton points out and I make no comment on, was centred on pubs — so that the credit risk was minimised. The owners of shops and pubs knew their customers very well and so were perfectly capable of deciding whether to accept cheques (or just IOUs) from those customers. And since the customers also knew each other very well, they too could make sensible decisions about which paper to accept.

Is there a business in ID or not?

Greyscale backing image
[Dave Birch] I spent the day at the seminar on the business use of ID cards at the EEMA/Digital Identity Forum seminar sponsored by Consult Hyperion at the British Computer Society. The presentations are available from the EEMA web site so there's no need to go through all of them here, but I just wanted to make a couple of points that came out of the day. The event was kicked off by the Parliamentary Under-Secretary for Identity, Meg Hiller. Meg gave an overview of where the UK national identity card scheme is now, and where it will be going. She kindly agreed to stay for an extended question and answer session, and just to show how modern we are I've posted a couple of minutes of this up on YouTube. She gave a couple of examples where businesses might want to use the cards, which was the point of the seminar. The example of video rental was once again to the fore, as well as banks. Meg also said that retailers could see the benefit of requiring an identity card to be presented for certain services and this set me wondering what kind of retailers these might be. I can see that retailers might need to know whether you are 16 to buy glue, or 18 to buy beer or whatever, but they don't need to know who you are. The more I thought about it, the more I thought that there is a real distinction between retail transactions where the retailer needs to know who you are, and retail transactions where the retailer wants to know who you are (and, conversely, in some cases you might want them to know who you are, because of warranties or something), and retail transactions where the retailer doesn't care who you are but needs to uniquely recognise you because of loyalty schemes or promotions. I have to say I was left unconvinced by the retail example. Her public sector arguments were much better, because it is a common an infuriating experience to have to keep giving your name and address and personal details to various departments over and over again. The example that Meg gave was of going through maternity services in the NHS, where she has to keep filling out the same personal information over and over again. I didn't think that was a good example, because the current government has spent TWELVE BILLION POUNDS on the computerisation of NHS patient records. It doesn't automatically follow that another few billion on the identity scheme would make any difference to her experience interacting with her local council, hospital or schools. Meg was also right to say that it's frustrating to have to fill out forms online, and indeed it is, but we had an afternoon presentation form the chief security architect at IPS, Andy Smith, and it was not clear to me from his description quite how the scheme is going to help here. Perhaps more technically-informed delegates could explain further.

On a roll

Greyscale backing image
[Dave Birch] The roll-out of contactless payment cards in the UK got a big boost when Barclayss announced that it would be converting several million cards this year.

From March, most Barclays debit cards that are issued or reissued will have contactless technology built in as standard. More than 3 million customers are expected to be using contactless debit cards by the end of the year.

[From Barclays to roll out contactless debit cards to all customers | 6 Jan 2009 | ComputerWeekly.com]

I’m still not seeing too many terminals out there, though, and I’m still concerned that I’m not seeing terminals in the places where cash replacement makes the most sense (car parks, that kind of thing). Still, where contactless is being used already, both at retail POS and in transport, it does seem to deliver the claimed benefits — speed and convenience — so we should be seeing more terminals soon. Actually, I’ve already seen lots more terminals: I’ve noticed that many of the ticket machines on South West Trains in England now have contactless interfaces installed. They don’t actually work yet, but let’s not run before we can walk!

Direct to debit

Greyscale backing image
[Dave Birch] One impact of the credit crunch, or whatever you want to call it, is that consumers are shifting their spending from credit cards to debit cards. Or, more accurately, consumers are shifting their spending from credit cards to debit cards even more quickly than they were before. This is hardly news, as it has been recognised for some time that debit volumes are growing substantially faster than debit transactions.

debit purchases are expected to climb 13% in 2008, to $1.2 trillion, according to The Nilson Report, an industry newsletter—compared with a 3% rise, to $1.9 trillion, for credit-card transactions. At Visa (V), the No. 1 card company, debit spending could surpass credit this year.

[From The Steady Ascent of the Debit Card – BusinessWeek]

Debit is clearly a product that consumers like. The debit space is not only attracting issuers and consumers, but others as well, with innovative products extending the reach. An example that caught my eye last year, illustrating an area where there is considerable growth potential for 2009, was the use of the debit infrastructure for welfare payments.

Under the five-year agreement, unemployment insurance benefits will be available on a MasterCard-branded debit card that can be used to access funds at banks and ATMs, and to pay for goods and services. Through a partnership with Bank of Oklahoma, cardholders will receive special opportunities for fee-free ATM and teller withdrawals.

[From Finextra: ACS provides debit cards for unemployment benefits in Oklahoma]

This kind of scheme shows that it is new applications, as well as new merchants and new customers, that will drive debit (and, I am convinced, pre-paid) in the near future.

Business and ID cards

Greyscale backing image
[Dave Birch] Just a quick reminder about the Digital Identity Forum’s joint seminar with EEMA at the British Computer Society in London on January 29th. This seminar, sponsored by Consult Hyperion, will be looking at the business opportunities that might arise from the introduction of the UK national identity card. You can register for the seminar at the EEMA web site. The event will be chaired by John Elliott of Consult Hyperion, who has considerable international experience of designing national ID card schemes. With speakers and panelists including

  • Meg Hillier, the Parliamentary Under Secretary for Identity.
  • Martin Linda, Siemens PLC.
  • Frank Layman, Federal Civil Service Information and Communication Technology department, Belgium.
  • Andy Smith, Identity and Passport Service.
  • David Blanco, Tractis, Spain.
  • Colin Whittaker, APACS.
  • Me.

it should be a useful day out and will hopefully lead to some genuine innovation. Whatever your opinions about ID cards — and I’ve made mine plain — the fact is that the first ones have already been issued. Since the UK scheme is now here, it makes sense for business to look at the opportunities that have arisen around ID cards in other markets, for both online and offline use, in the public and private sectors.

Defending cash

Greyscale backing image
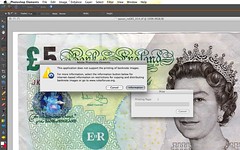
[Dave Birch] I was listening to a recent episode of Skepticality, about the TV show “Numb3rs”. The presenters were interviewing one of the writers about the making the show and they made a comment that caught my money-obsessed ear. The writers said that they had been researching a show about counterfeiting and during the course of this research they had copied a $20 bill on a photocopier to see how well it came out. Shortly thereafter they got a phone call from the US Treasury! The photocopier was online, and phones home when someone tries to copy money! (Incidentally, the Treasury guys weren’t very happy to hear the proposed plotline about the FBI investigating some counterfeiters because it’s the Secret Service — until 2002 part of the Treasury — who take care of that.) I thought they might be exaggerating, but it turns out that not only do some photocopiers have this feature built in to them, there are many printer drivers that won’t print scanned bills!!. Ever-vigilant for the cause of monetary trivia, I tried it out myself. I scanned a fiver and tried to print it, and I got this error message.

Contactless Christmas

Greyscale backing image
[Dave Birch] Hhhmmm. Only a couple more shopping days left until Xmas, time for a real man to start thinking about presents. What would make a good present for a Digital Money Denizen this year?

The disgruntled commuter, the perpetual pessimist, the misanthrope, the ironist [which covers a large percentage of the people we know!]: Whether you find in your daily commute something soul-sucking or rather darkly comedic, Bad Oyster knows that public transit ain’t all a pleasure cruise. Its Sardines, Roulette and Mind the Gap (‘between your expectations and the service provided’) wallets (£2.99) are like a miniature dose of defensive humour for your harried journey.

[From Londonist: Santa’s Lap: Designer Oyster Card Holders]

Not bad. But these are about accessorising (is that the word? My spell check is unconvinced) the payment instrument rather than the payment instrument itself. Meanwhile, over in Hong Kong, they’re showing what can be done with a bit of imagination.

This premium and stylish Octopus series offers four adorable animal designs for customers to choose from, each gorgeously adorned with colourful crystals. Each Octopus Ornament also comes with a beautiful charm and chain which can be easily attached to a handbag, mobile phone or MP3 player, or worn on the wrist as an accessory, adding a touch of dazzling glamour! Each Octopus Ornament design is beautifully packed in an exquisite gift box, making it a perfect treat for family and loved ones.

Combining sparkling glamour and payment convenience, Octopus Ornaments are for sale at only HK$328 each (not including any deposit or initial stored value) at 7-Eleven outlets in Central, Admiralty, Wan Chai, Causeway Bay, Tsim Sha Tsui, Mong Kok and Sha Tin starting tomorrow (4 December 2008). Only a limited quantity is available.

Like all Octopus products, Octopus Ornaments can be used on public transport and at more than 5,000 retail outlets across Hong Kong.

[From Octopus Holdings Limited – Press Releases]

I still have the same boring old Oyster card I bought years ago, although I rarely use it anymore because of my splendid Barclays OnePulse card. It sits at the bottom of my rucksack, only used to help friends or family members who have forgotten theirs. But if I could get a Hello Kitty Oyster tag for my bag, I would. In fact, I’d probably get several, so that I could pay in the most appropriately fashionable way.

Subscribe to our newsletter

You have successfully subscribed to the newsletter

There was an error while trying to send your request. Please try again.

By accepting the Terms, you consent to Consult Hyperion communicating with you regarding our events, reports and services through our regular newsletter. You can unsubscribe anytime through our newsletters or by emailing us.